

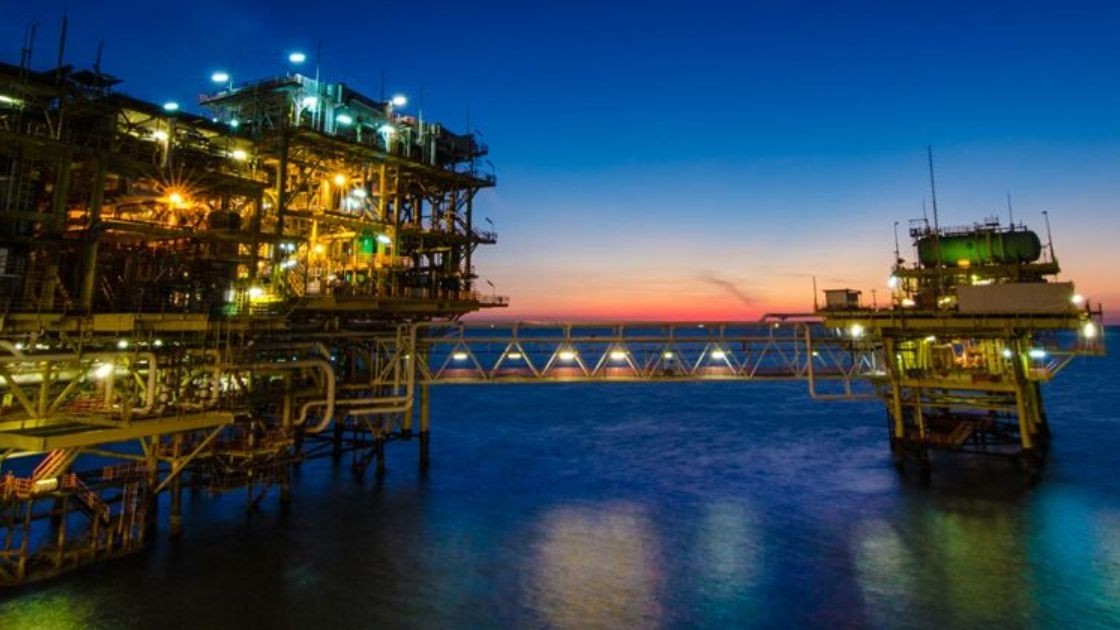
Large integrated oil and gas corporations have fundamentally shifted their business strategy since 2020, prioritizing shareholder returns through dividends and buybacks over expansion investments. The five largest publicly traded companies—Exxon Mobil, Chevron, British Petroleum, Shell, and TotalEnergies—have collectively allocated more than $100 billion annually to shareholder distributions, consuming approximately 80% of their combined earnings.
This capital allocation strategy has significantly constrained spending on exploration and development activities. According to EY analysis, the 30 largest U.S. publicly traded exploration and production companies reduced capital expenditures by 49% year-over-year in 2025, with exploration budgets declining 11% to $4.8 billion. Acquisitions spending fell 70% as consolidation activity slowed. These 30 companies represent roughly 43% of total U.S. oil and gas production.
Despite reduced spending, oil output from this cohort reached record levels in 2025, with revenue increasing 7%. This apparent contradiction reflects technological and operational advances in the industry. Horizontal drilling now extends wells three miles or longer, allowing single rigs to access larger volumes of oil-bearing rock. Simultaneous well completions have reduced execution timelines and service costs. Additionally, operators have deployed artificial intelligence and machine learning to optimize production efficiency, extend asset lifecycles, and reduce operating expenses through real-time analysis of geological and operational data.
The shale revolution fundamentally altered industry economics by enabling rapid production cycles—wells can be drilled, fractured, and producing within months rather than years. This contrasts with traditional offshore and megafield projects requiring lengthy development periods. Producers have also relied on inventories of drilled but uncompleted wells to maintain output without new drilling investments. However, the U.S. DUC inventory declined to its lowest level since tracking began in 2013, reaching approximately 4,972 wells in May.
This production strategy carries long-term implications. Oil reserve additions from discoveries and extensions declined 11% year-over-year, marking the first time in five years that replacements failed to match production volumes. This constraint reduces flexibility for rapidly increasing output during global supply disruptions. Natural gas represents a contrasting picture, with reserves increasing 14% and discoveries rising 21%, positioning the fuel as increasingly central to energy security and infrastructure development.
Article Attribution | Read More at Article Source
Article summary produced by Claude AI